Every debt payoff story starts the same way: somebody finally writes every balance down in one place. A debt spreadsheet is that place - one grid that shows what you owe, what it costs you, and which payment kills which debt. Here is exactly how to build one tonight, in Google Sheets or Excel, with the formulas that do the boring maths for you.
A working debt spreadsheet answers three questions at a glance: how much do I owe in total, which debt is most expensive, and when does it end. Everything on the grid exists to answer those three.
That means one row per debt and five columns to start: the name of the debt, the current balance, the interest rate, the minimum monthly payment, and the due date. If a row does not help answer the three questions, it is decoration - leave it out for now.
Open a blank sheet. In row 1, type the headers: Debt, Balance, Rate, Minimum, Due date. Then list every debt you have - credit cards, personal loans, car loan, student loan, the store card you forgot about. One row each, with the real balance from the latest statement, not a guess.
Under the last row, add a Total row: =SUM(B2:B10) under Balance, and =SUM(D2:D10) under Minimum. That total balance number is the one you will watch shrink. Most people have never seen it as a single number - it is usually smaller than the fear and bigger than the hope, and either way it is better to know.
Three formulas carry the whole spreadsheet. First, monthly interest cost per debt: =B2*C2/12 - balance times rate divided by twelve. Add a column for it and sort by it; the top row is where your money leaks fastest.
Second, months to payoff at the current payment: =NPER(C2/12,-D2,B2) gives you how many months a debt survives if you only pay the minimum. The answer is usually horrifying, which is the point - it turns "someday" into a date.
Third, the payoff order helper. Add a column called Extra and type whatever extra amount you can pay monthly, even 500 rupees or 20 dollars. Your snowball or avalanche plan lives in this column: all of it goes to one target debt while the rest get minimums.
Avalanche means your extra money attacks the highest interest rate first - the mathematically cheapest route. Snowball means it attacks the smallest balance first - the fastest first win. To use avalanche, sort your sheet by the Rate column, largest at the top. To use snowball, sort by Balance, smallest at the top. The spreadsheet does not care which religion you follow; it just needs the target debt visible at the top.
When the target debt hits zero, delete nothing. Mark it paid, move its entire payment - minimum plus extra - onto the next row. That rolling payment is the engine of both methods, and watching it grow is the most satisfying part of the whole sheet.
Numbers fade; a line on a chart does not. Add one more small table: month in column A, total balance in column B. On the first of every month, copy your total balance into the next row. Select the table, Insert, Chart, line chart.
This takes ninety seconds a month and it is the difference between a spreadsheet you abandon and one you finish. A declining line is proof. On the months where willpower is thin, the chart does the arguing for you.
The same setup works as an excel spreadsheet to keep track of credit card debt - every formula above is identical in Excel and Google Sheets. If a card balance moves between cards in a balance transfer, keep the row and just rename it, so your total-balance history stays honest.
One Excel-only tip: use a real date column for due dates and conditional formatting to turn the cell red inside five days of the due date. Late fees are the dumbest way to lose the fight, and a red cell is cheaper than a reminder app.
If you would rather skip the build, our debt payoff spreadsheet has all of this wired up - the payoff formulas, snowball and avalanche ordering, a debt payoff tracker printable view, and the monthly chart - tested with dummy data before we listed it. Whether you build or borrow, the important row is the Total. Make it smaller every month, and the rest is arithmetic.
One row per debt with five columns - name, balance, rate, minimum payment, due date - then a SUM row for the total balance. Add =NPER(rate/12,-payment,balance) to see months to payoff, and a monthly line chart of the total to stay motivated.
At minimum: debt name, current balance, interest rate, minimum payment and due date. Useful extras: monthly interest cost, an extra-payment column, and a paid-off marker so finished debts stay visible as wins.
Yes - the same layout works as an excel spreadsheet to keep track of credit card debt, and every formula is identical. Add conditional formatting on the due-date column so upcoming payments turn red before they cost you a late fee.
our debt payoff spreadsheet · what is a snowball method · a savings tracker for what comes after
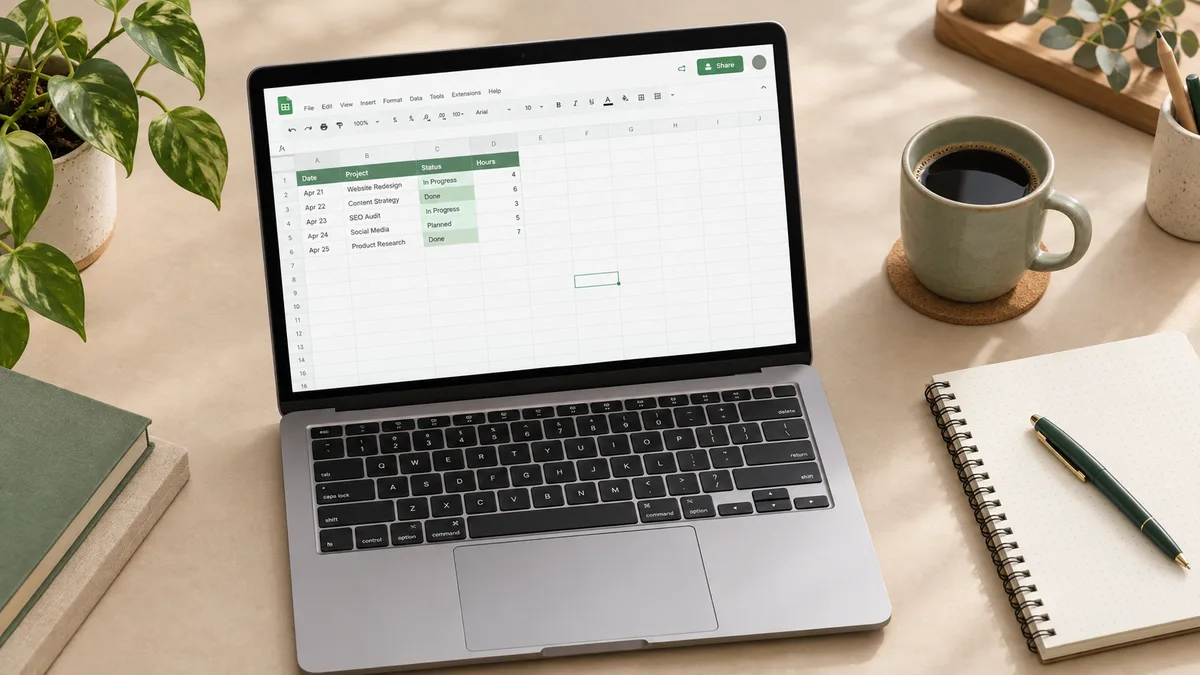
How to use Google Sheets from zero: cells, formulas, formatting and sharing, explained with small real examples. No jargon, no prior Excel needed.
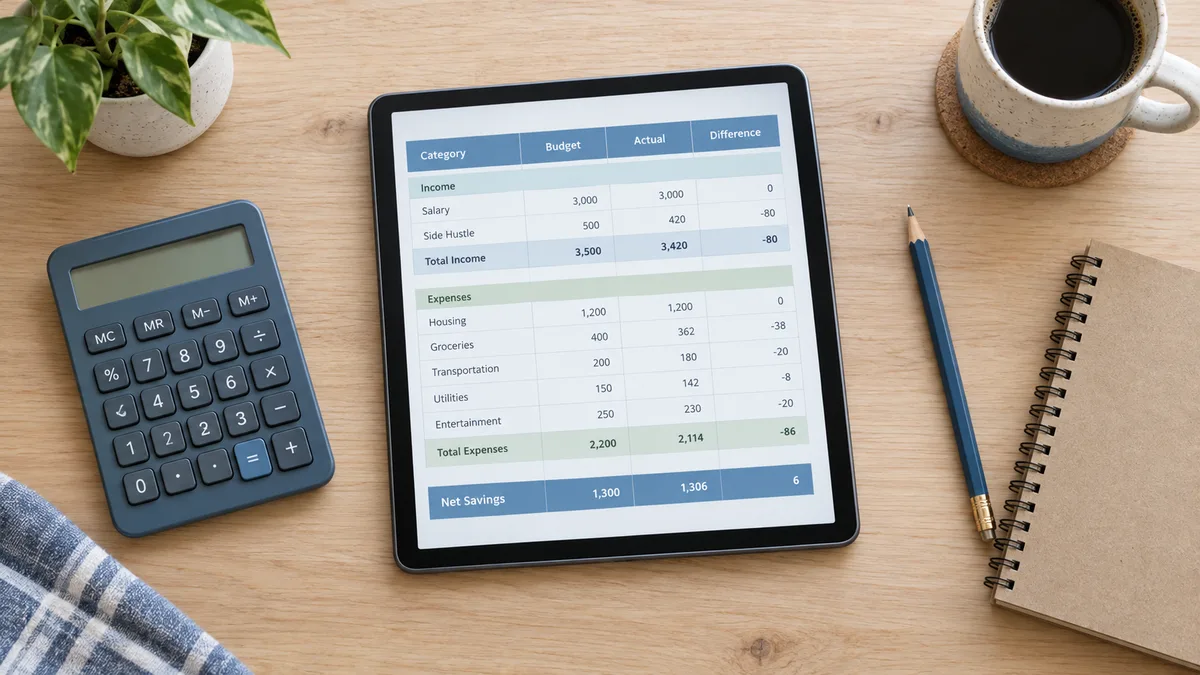
How to make a spreadsheet from a blank grid: plan the columns, add formulas, format it clean, and turn it into a reusable template. A 15-minute build.